Flood-Insurance Gaps Meet a Fast-Moving Mortgage Market
This week’s coverage is a reminder that insurance details and financing assumptions deserve a fresh look before a renewal, purchase, refinance, or loss.
4 min read
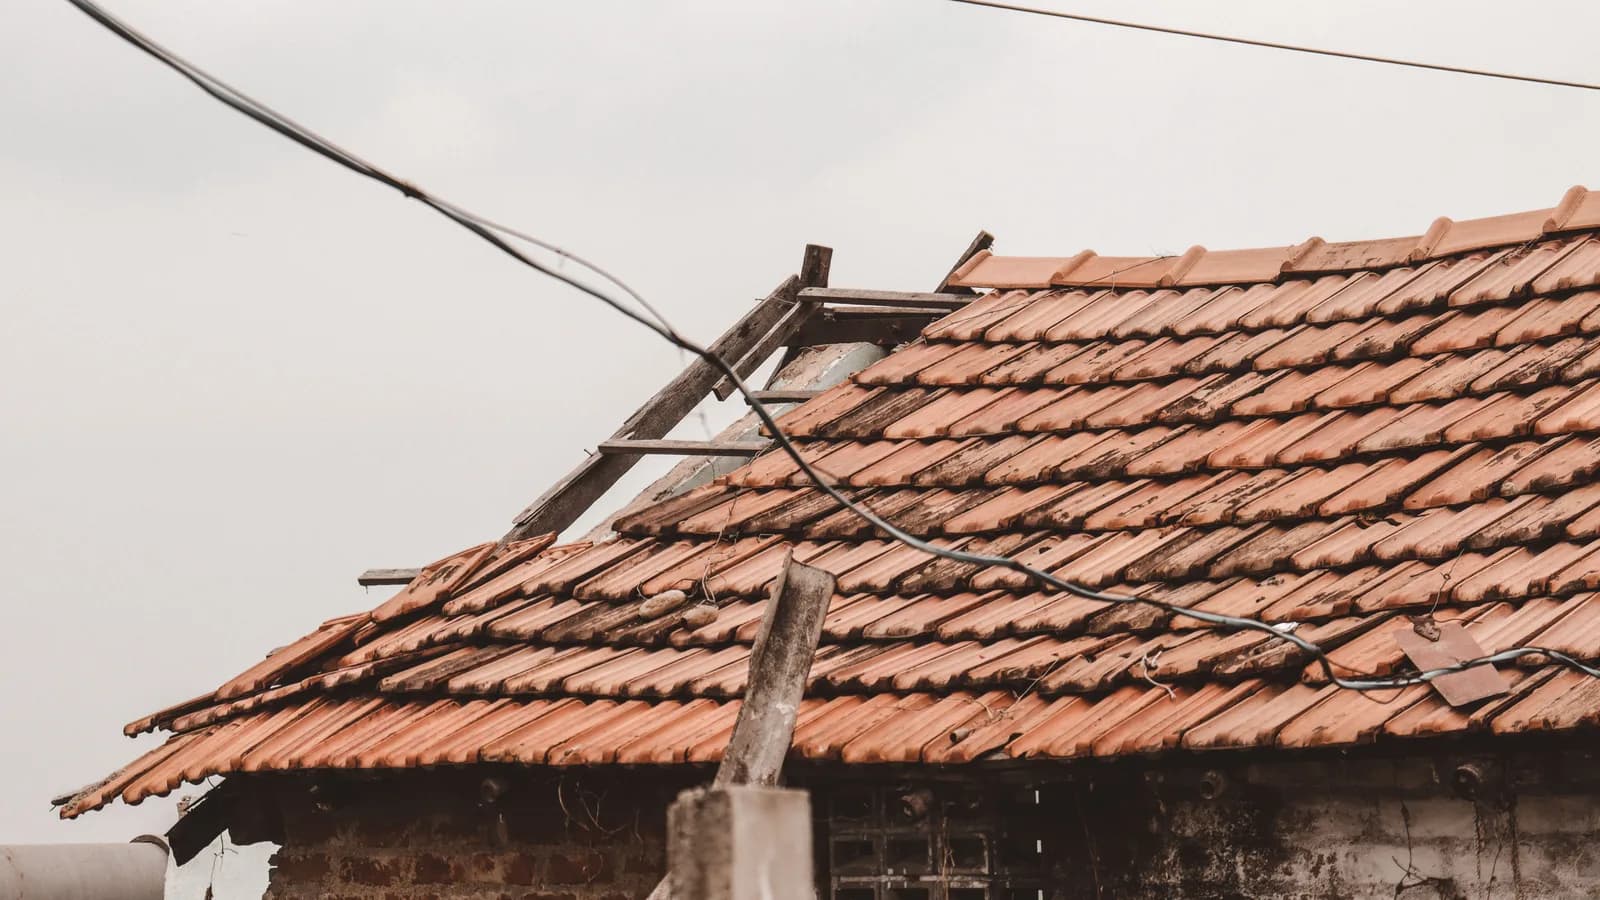
Photo: GOWTHAM AGM / Pexels
In this article
This week’s coverage is a reminder that insurance details and financing assumptions deserve a fresh look before a renewal, purchase, refinance, or loss.
Flood Gaps, Roof Questions, and Wildfire Data Put Insurance Details Under a Microscope
Associated Press coverage carried by WRAL and MyMotherLode found a large national gap between the share of properties with federal flood coverage and the share facing severe or extreme flood risk.
The reports also found that standard homeowners coverage does not cover flood damage, while FEMA maps can miss flooding caused by heavy inland rain.
That gap is especially visible in eastern Kentucky, where the coverage share in the area struck by the 2022 floods was far below the share of properties facing severe or extreme risk.
Elsewhere, the week’s coverage shows insurers refining how they assess property risk: Live Insurance News reported Texas regulators proposed a rule barring denials or nonrenewals based solely on roof age, while Carrier Management reported that some California carriers have reduced exposure or limited new business and that parcel-level wildfire modeling can be more precise than broad ZIP-code assessments.
What this means for you
- Treat flood protection as a separate coverage question instead of assuming all water damage is included in a standard policy.
- An older roof is not the same thing as a poorly maintained roof, so keep clear records of inspections, repairs, and maintenance.
- If wildfire exposure is a concern, focus on the condition of your lot and home rather than relying only on the reputation of the surrounding area.
- Rental-property owners should maintain dated condition records for both the building and major systems.
What to do
- Read your declarations page and identify whether flood coverage is separate from your homeowners policy.
- Photograph the roof, exterior, drainage areas, and major belongings before your next renewal.
- Use the Home insurance renewal review guide to prepare questions for your insurer or agent.
- Build or update a room-by-room record with the Home inventory for insurance claims guide.
- Use the Monthly home cost audit guide to include premiums, deductibles, and reserves in your regular property budget.
Related on 4Homes: Home insurance renewal review guide, Home inventory for insurance claims guide, Monthly home cost audit guide.
Sources: wral.com, mymotherlode.com, liveinsurancenews.com, Carrier Management.
Get your personalized numbers →
Get startedBond-Market Volatility Keeps Mortgage Planning on a Shorter Clock
Realtor.com reported that mortgage pricing moved quickly this week during a broad bond-market selloff, with energy costs, inflation concerns, and federal-deficit worries among the factors cited in the coverage.
Mortgage Professional America reported that Cotality economist Selma Hepp sees long-term Treasury-market forces as a stronger influence on mortgage pricing than Federal Reserve decisions, and that builders are offering incentives and rate buydowns.
CNBC featured Mortgage News Daily chief operating officer Matthew Graham in a discussion of what borrowers could expect from the fixed-rate mortgage market.
Taken together, the reports suggest that bond-market conditions can change a financing conversation quickly, even when most attention is fixed on the next Federal Reserve meeting.
What this means for you
- A payment estimate can change between house hunting, making an offer, and locking a loan.
- Seller credits, builder incentives, and loan structure can matter as much as a lender’s headline quote on a given day.
- Rental-property buyers should test whether expected rent supports the payment, reserves, repairs, and insurance costs.
- Avoid building a purchase or refinance decision around a single expected policy announcement.
What to do
- Recalculate your expected payment before submitting an offer or accepting a counteroffer with the Mortgage payment calculator.
- Compare a refinance against your current loan using the Refinance calculator before paying fees or changing terms.
- Run both repayment timelines through the 15 vs. 30-year calculator and compare the monthly budget impact.
- Ask lenders to explain the lock period, points, closing costs, and how long the quoted terms remain available.
Related on 4Homes: Mortgage payment calculator, Refinance calculator, 15 vs. 30-year calculator.
Sources: Realtor.com News, Mortgage Professional America, CNBC Real Estate.
The 4Homes weekly email
Every Tuesday: what changed for homeowners this week, plus our newest guides.
No spam. Unsubscribe anytime.
FAQ
Frequently asked questions
Can an insurer reject coverage because my roof is old?+
Live Insurance News reported that Texas regulators proposed a rule that would prevent insurers from denying or declining to renew homeowners coverage solely because of roof age. The report says insurers could still act when an inspection finds damage, deterioration, or poor maintenance.